ADU Construction Loans in California
An ADU construction loan pays your builder in stages as the unit goes up and passes inspection. Because it can lend on the finished value, it suits California owners whose equity does not stretch to the full budget.
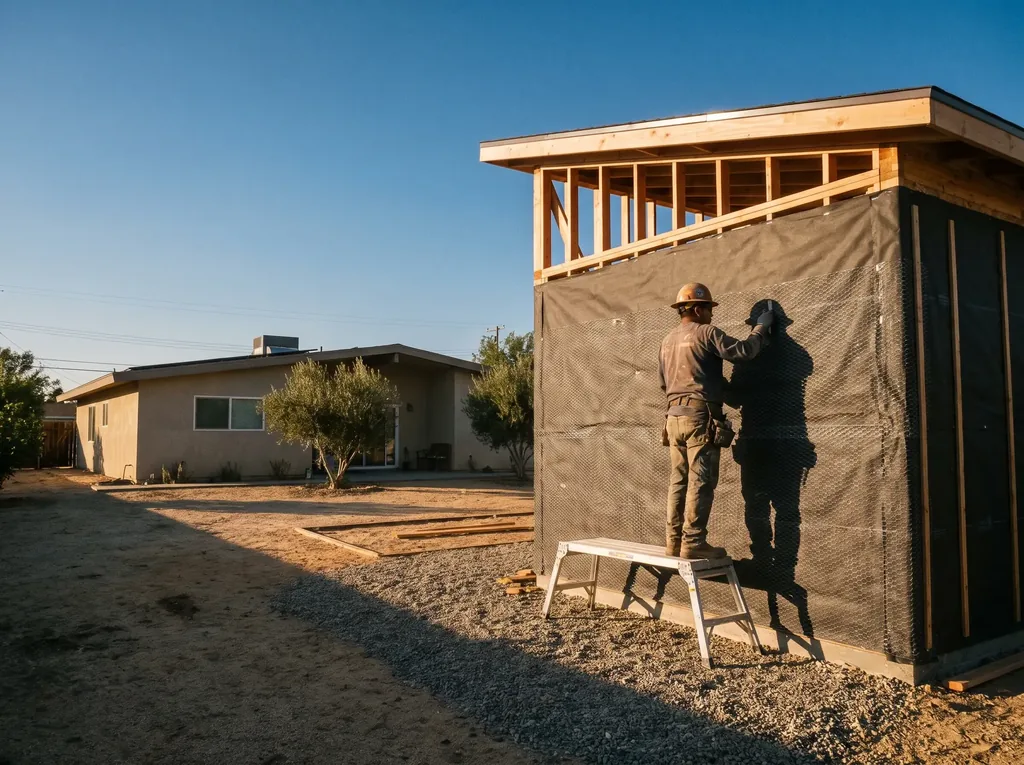
- We explain every option, not just one product
- Matched with lenders who finance ADUs
- No obligation to take any offer
How a construction loan works on a California ADU
The lender approves a budget, then releases money in draws after inspections. During the build you often pay interest only on what has been drawn. When the unit is finished the loan converts to a permanent mortgage in a one time close, or you refinance in a two time close.
California permitting sets the pace. The lender wants approved plans, a budget and a qualified builder, and the permit comes first. State law requires cities to act on a complete ADU application within a set review period, which helps you time the closing. Confirm with your city or county.
At a glance
- Best for: owners whose equity falls short of the budget
- How money arrives: draws after inspections
- During the build: often interest only
- What lenders check: credit, income, plans, budget, builder and an as completed appraisal
Construction loan pros and cons for a California ADU
Pros
- Can lend on the finished value, not just today's equity
- Draws mean you never pay ahead of the work
- Interest only during the build keeps early payments lower
- A one time close avoids a second closing
Cons
- More paperwork: plans, budget and builder approval
- Fewer lenders offer them for ADUs
- Permit or inspection delays can hold up draws
- Your builder has to be acceptable to the lender
When another route fits better
If your equity covers the budget, a HELOC is usually simpler. If you qualify, the CalHFA grant may reimburse some early costs. Before you commit, run your quoted terms through a calculator.
California HELOC for an ADU
Draw on your equity as builder invoices arrive.
CalHFA ADU Grant Program
What the state grant reimburses and how to check whether it is currently funded.
ADU loan calculator
Estimate a payment from the rate, term and amount a lender quoted you.
California ADU construction loan questions
Which is better, a home loan or a construction loan?
They do different jobs. A home equity loan or HELOC borrows against the house as it is today. A construction loan pays out during the build and can lend on the finished value, so it may go further.
What's the best way to finance an ADU?
It depends on your equity and your current mortgage. Many California owners with strong equity and a low first mortgage rate use a HELOC. Owners with less equity often need a construction or renovation loan based on the finished value.
What are the common mistakes when building an ADU?
Starting without a full budget, forgetting permit fees and utility connections, and lining up financing after the plans are done. Talk to a lender early, so the loan type, budget and permit timeline fit together.
Talk to a lender who finances ADUs
Tell us about your project, your rough budget and your timeline. We will connect you with a lender who offers ADU construction loans in California so you can compare real terms.
Thanks. We have your details and a lender who finances ADUs will be in touch, usually within one business day.